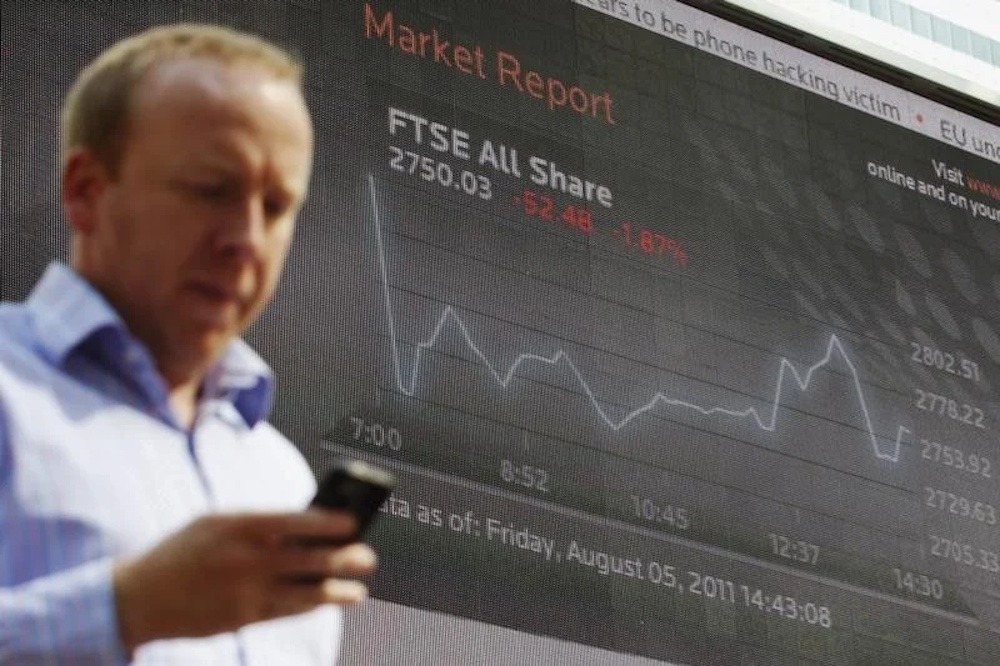
On Wednesday, the UK’s FTSE 100 experienced a slight decline following three consecutive days of gains, primarily influenced by banking stocks. The uptick in oil prices and the rise in bond yields contributed to a cautious sentiment among investors.
The blue-chip FTSE 100 index fell 0.4% to 10,498.53 points by 0948, while the midcap FTSE 250 slipped 0.2%.
- Oil prices experienced an uptick, with Brent futures maintaining a position above $100 per barrel, as investors assessed the implications of increased Gulf exports in contrast to ongoing supply uncertainties stemming from the Middle East conflict and an impending storm threatening US oil-producing areas.
- Shell expects third-quarter refining margins to jump to a record $42 a barrel, sharply above $24 a barrel in the previous quarter.
- Shares in the oil major experienced an increase of 0.7%.
- British 10-year borrowing costs increased, following the rise in oil prices and US Treasury yields, reaching their highest level since October 1, when they approached a near 20-year high.
- Investors also anticipated the release of minutes from the Federal Reserve’s most recent meeting for additional insights into the trajectory of US monetary policy and the timing of potential interest-rate reductions.
- Heavyweight banking stocks led declines on the benchmark index, with HSBC, Standard Chartered, and Barclays falling between 2% and 3%.
- Source reported that HSBC plans significant job reductions in its UK wealth business as part of a wider initiative aimed at enhancing efficiency through artificial intelligence.
- Pennon Group opened a new tab and tumbled 21%, making it the biggest decliner on the FTSE 250, after the water utility launched a fully underwritten £550 million rights issue and cut its dividend.
- Shares in protective equipment provider Avon Technologies jumped 14% after it stated that annual results were anticipated to exceed market expectations.
- British house prices remained unchanged in September following their initial annual decline since 2023 in August, as reported by Lloyds data, which fell short of analysts’ expectations.